


Five Years of Growth How We Adapted, Survived Market Shocks and Built a Stronger Business

Five years in business can feel like a lifetime when the market keeps changing under your feet.
When we started trading, the plan was simple enough: build a good product, serve customers well and provide the owner with a living. That still matters. It always will. But the last five years have taught us that good intentions are not enough. A business also needs discipline, cash control, flexible people, better materials, and the courage to change direction before the numbers force the issue.
We have faced sudden market shocks, rising costs, changing customer habits, and pressure on discretionary spending. The Liz Truss mini-budget created a sharp shock in confidence and in the wider economy. Inflation pushed up our costs and made customers more careful with their money. At the same time, the market became more competitive and less predictable.
We kept trading by making hard choices early. We put emergency funding into the business when we needed to protect it. We changed suppliers. We reduced waste. We moved towards higher value clients rather than chasing volume for its own sake. We developed new products for a different demographic. We grew and trained the team so we could offer more, with higher quality and more flexibility.
This is the story of how we adapted, where we made changes, and why the business is now stronger than it was at the start.

The market changed, so we changed with it
The early stage of any business often rewards energy. You say yes to more work, take on a broad mix of customers, and learn quickly from every order. That approach helped us get started, but it also showed us the limits of volume-led growth.
As the market shifted, it became clear that doing more of everything was not the best route forward. More orders did not always mean better profit. More enquiries did not always lead to better customers. More activity could also create more pressure, more waste, and more room for mistakes.
We began to ask better questions.
Which products gave customers the most value?
Which types of work made best use of our skills?
Where were margins being lost?
Which customers valued quality enough to pay for it?
Which products could appeal to a new demographic?
That thinking changed the shape of the business.
Instead of trying to be the cheapest option or the busiest supplier, we focused more on the customers who wanted a better product and a better service. That meant accepting that growth would not always look like more volume. Sometimes growth meant fewer orders, handled better, with stronger margins and less strain on the team.
It also meant developing new products. We looked at where demand was moving, what customers were asking for, and what different groups valued. Some wanted a more premium finish. Some wanted longer-lasting materials. Some wanted a more tailored service. Some wanted products that felt less standard and more personal.
That opened up a new route. By improving the offer, we could appeal to customers who were willing to invest more in quality. We could also move away from a constant race to the bottom on price.
That was one of the most important shifts in the past five years: choosing the right work, not just more work.
Emergency funding helped us survive the sharpest shocks
No business owner wants to put emergency funding into a company just to keep it steady. But sometimes survival requires quick action.
The shock that followed the Liz Truss mini-budget was one of those moments. Confidence dropped. Costs and borrowing concerns became a bigger conversation. Customers became more cautious. For a business that relies at least partly on discretionary spending, that matters straight away.
When people feel uncertain, they pause. They delay. They compare harder. They spend less freely.
We had to respond with urgency. Emergency funding gave us breathing space. It allowed us to keep trading, protect key parts of the business, and avoid making panic decisions that could have damaged us in the long term.
That funding was not a magic fix. It was a bridge. The real work came next.
We had to review costs line by line. We had to look at stock, materials, labour, pricing, and waste. We had to protect cash without weakening the product. That is a difficult balance. Cut too much and quality falls. Do nothing and margins disappear.
The lesson was clear: cash buys time, but only discipline turns that time into recovery.
Emergency funding helped us get through the immediate shock. Better decisions helped us build beyond it.
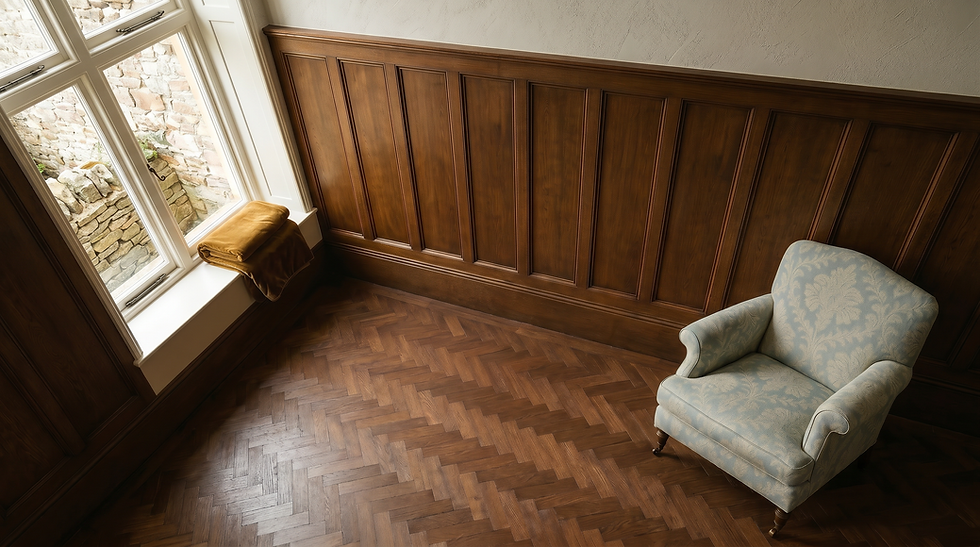
Making products from real wood heritage based designs appeals to a new demographic of customers.
Inflation affected the business from both sides.
Our costs went up. Materials became more expensive. Supplier prices changed more often. Transport and energy pressures fed into the wider supply chain. At the same time, customers felt pressure on their own household budgets, which changed how they made buying decisions.
That combination can squeeze a business quickly. If costs rise and customers become more price sensitive, margins can shrink before you notice. A product that once worked commercially may no longer make sense at the same price. A material that once felt good value may become too expensive unless the customer clearly sees the benefit.
We responded by getting closer to the numbers.
We reviewed which products carried healthy margins and which ones were too fragile. We looked at materials that created too much waste. We examined processes that took longer than expected. We paid closer attention to rework, offcuts, delivery costs, and supplier reliability.
Small losses matter more in a tight market. A few wasted materials here, a little extra labour there, a supplier delay that causes a job to overrun, all of it eats into profit.
We did not simply pass every increase on to customers. That would have been too blunt. Instead, we worked on the things we could control.
We sourced new suppliers where it made sense. We compared quality, reliability, lead times, and value. We looked for materials that supported a better product without creating unnecessary cost. We reduced waste by planning more carefully. We improved stock control. We made pricing more realistic.
The goal was not to make everything cheaper. The goal was to make every product work better commercially.
That distinction matters. Cheap inputs can create expensive problems. Higher quality materials can reduce waste, improve finish, lower complaints, and support a stronger price. In many cases, better materials helped us protect the customer experience and the margin at the same time.
Moving upmarket changed how we measured success
For a long time, volume can look like success. A full order book feels reassuring. A busy team feels productive. Lots of enquiries can make a business feel healthy.
But volume without margin can be dangerous.
One of our biggest changes was shifting towards higher value clients with less volume. That meant becoming more selective about the work we took on and clearer about the value we offered.
Higher value clients tend to care about more than the lowest price. They care about quality, finish, reliability, service, and confidence. They want the job done properly. They are often willing to pay more when they can see the difference.
That pushed us to raise our standards across the business.
We had to improve materials. We had to sharpen communication. We had to train staff. We had to make sure our products justified the price. We had to deliver a consistent experience, not just a good result on a lucky day.
This approach also reduced some of the pressure that comes from chasing high volume. Less volume does not mean less work. In many cases, higher value work demands more attention and more skill. But it can create a healthier business if it is priced properly and managed well.
The benefits showed up in several ways:
Better margins on the right products
Less pressure to win every enquiry
More time to focus on quality
Fewer low-value jobs that stretched the team
A stronger fit between customer expectations and our offer
This shift gave us a clearer identity. We were no longer trying to serve every part of the market in the same way. We were building a business around quality, value, and skill.

New products helped us reach a different demographic
Adapting to a changing market also meant looking beyond our original customer base.
Customer needs changed over the five years. Some people became more careful with spending, while others became more selective. Many wanted products that felt more considered, more durable, or better suited to their lifestyle. That gave us an opportunity to create products for a different demographic.
We did not want to create new products just for the sake of it. Every new offer had to earn its place. It had to fit our skills, use materials well, appeal to customers with real demand, and support better margins.
The best product development came from listening closely. We paid attention to repeated questions, common objections, and small clues in customer behaviour. When several customers asked for similar changes, finishes, sizes, features, or service options, we treated that as useful evidence.
This helped us create products that felt like a natural extension of the business rather than a distraction. It also gave staff new challenges and new skills to build.
New products helped in three important ways.
They gave existing customers more choice. They helped us appeal to people who may not have bought from us before. They reduced our reliance on one narrow part of the market.
That last point matters. A business that depends too heavily on one product, one audience, or one price point can become vulnerable. When demand changes, there is nowhere to move. A broader but still focused product range gives the business more resilience.
Growing the workforce gave us more flexibility
Survival is often about cash and cost control. Growth is about people.
As demand changed, we needed a team that could flex with it. That meant growing the workforce, but in a careful way. Hiring only works when it adds capability, not just headcount.
More people allowed us to respond to demand more effectively. It gave us more cover at busy times. It helped reduce bottlenecks. It also allowed us to offer other services that would have been difficult with a smaller team.
Flexibility became a key part of the business. When one area was quiet, skills could be used elsewhere. When demand rose, we had more capacity to respond. When new products needed support, we had people who could learn and take ownership.
A larger team also brought fresh ideas. People notice different problems. They see better ways to handle materials, set up work, communicate with customers, or finish a product. When that knowledge is shared, the whole business improves.
But growth in the workforce also brings responsibility. More people means more training, clearer systems, and better communication. Without that, a bigger team can become slower rather than stronger.
That is why training became such a major part of our strategy.
Training raised the quality of what we could offer
Training has been one of the best investments we have made.
As we moved towards higher value clients and higher quality products, we needed the skills to match. It was not enough to say we offered better work. The team had to deliver it consistently.
Training helped staff improve existing skills and learn new ones. It gave us more flexibility across the team. It meant we could offer a wider range of products without relying too heavily on one or two people. It also improved confidence, which matters when customers expect advice and high standards.
Better skills supported better quality. Better quality supported stronger pricing. Stronger pricing supported better margins. That cycle helped move the business away from survival mode and towards a healthier model.
Training also helped with waste. Skilled staff make better use of materials. They spot issues earlier. They understand how small mistakes affect cost and finish. They can prevent problems rather than fixing them later.
That becomes especially important when using higher quality materials. Premium materials can improve the final product, but they also make mistakes more expensive. Training reduces that risk.

What five years of trading has taught us
The business we run now is not the same as the one we started. It is more focused, more careful, and more resilient.
We have learned that growth is not always a straight line. Sometimes it means stepping back from the wrong work. Sometimes it means putting money in to protect the future. Sometimes it means changing suppliers, reviewing prices, or rebuilding a product range. Sometimes it means slowing down enough to improve quality before trying to grow again.
The biggest lessons are simple, but they are not always easy.
Margin matters more than activity. A busy business can still be weak if the work is priced badly or managed poorly.
Quality has to be built into the model. Better materials, better skills, and better processes need to support each other.
Cash control protects choice. When the market shocks you, breathing space can stop short-term pressure from becoming long-term damage.
People create resilience. A trained, flexible workforce gives the business more options when demand changes.
Adaptation has to be active. Waiting for the market to return to normal is not a strategy. The market may not return to what it was.
After five years, we are proud to still be trading, but survival is only part of the story. The real achievement is that the business has grown stronger through the pressure. We have a clearer offer, a better understanding of our margins, a broader range of products, a more skilled team, and a stronger sense of the customers we want to serve.
The next stage will bring new challenges. Costs will keep moving. Customer habits will keep changing. Competitors will keep adapting too. But we are in a better position because we have already learned how to respond.
Five years of trading has taught us this: a stronger business is not built by avoiding difficult periods. It is built by facing them honestly, making the right changes, and continuing to improve even when the market is uncertain.


Comments